

In this article
- What recovery options may be available after a pedestrian hit-and-run?
- Can your own insurance help if you were walking?
- What affects the value of a pedestrian hit-and-run claim?
- What evidence can support your recovery options?
- How can you organize insurance claims and payments?
- Why do deadlines and fault rules matter?
- Which recovery rules vary by state?
- Frequently Asked Questions
- Next Steps
After a pedestrian hit-and-run, you may be able to seek compensation through the driver’s insurance if the driver is identified, your own auto policy’s uninsured motorist coverage, health coverage, or a victim compensation program. The options that apply depend on policy language, state rules, the evidence, and the losses you can document.
Key Facts
- A driver’s identity is not always necessary to explore insurance options.
- Your own auto policy may provide coverage even when you were walking, depending on its terms and state law.
- Health insurance or other medical coverage may help pay treatment costs while a liability claim is pending.
- Victim compensation programs may help with certain expenses, subject to eligibility and program rules.
- Deadlines and fault rules vary by state, and insurance policies may have their own notice requirements.
What recovery options may be available after a pedestrian hit-and-run?
Several recovery options may be available after a pedestrian hit-and-run, even if the driver has not yet been found. If authorities identify the driver, you may pursue a claim against the driver’s auto liability insurance. If the driver remains unidentified or has no applicable insurance, uninsured motorist coverage may be worth checking.
Your own auto policy may include uninsured motorist protection that applies when you are struck as a pedestrian. Whether it does depends on the policy wording and state law, so review the policy or ask the insurer to explain its position in writing. You can also look at health insurance, medical payments coverage, or no-fault benefits, where available, to help address treatment costs.
Some states and local programs have victim compensation funds that may cover certain expenses after a qualifying crime, including some hit-and-run incidents. Eligibility, covered costs, application procedures, and deadlines differ. A claim can involve more than one source, but payments may affect how other claims are handled. Learn more about Pedestrian Hit-and-Run Accidents and the possible paths for seeking recovery.
- Identify every policy that could apply, including your own and policies covering household members.
- Ask insurers what coverage may apply and what documents or notice they require.
- Check whether a victim compensation program serves your area and whether you may qualify.
Can your own insurance help if you were walking?
Your own insurance may help after a pedestrian crash, but coverage depends on the specific policy and applicable state rules. Uninsured or underinsured motorist coverage may be available through your auto policy, and in some circumstances through a household member’s policy. Do not assume the coverage applies—or that it does not—without checking the policy and getting a clear explanation from the insurer.
Medical payments coverage or personal injury protection may also help pay eligible medical expenses, depending on the coverage you have and the state’s system. These benefits can have limits, exclusions, coordination rules, and filing requirements. Health insurance may be another source for treatment bills, though deductibles, co-pays, and reimbursement rights can affect your finances later.
Tell each insurer the crash involved a pedestrian and a driver who left the scene. Keep copies of policy documents, claim numbers, letters, and explanations of benefits. If an insurer says a policy does not apply, ask which policy term or rule supports that decision. The Pedestrian Accidents overview can help you understand common issues in pedestrian injury claims, but your coverage turns on the facts and documents for your situation.
- Gather the declarations pages and full policy wording for potentially relevant policies.
- Report the incident in the manner and timeframe required by each policy.
- Save written coverage decisions and ask about appeal or review procedures.
What affects the value of a pedestrian hit-and-run claim?
A claim’s potential value depends on the losses supported by evidence, the available insurance or other funds, and the rules that apply. Relevant losses may include medical expenses, income you missed, reduced ability to work, and the physical effects of the injury on daily life. The nature and duration of treatment can help show how the crash affected you, but no single factor determines a claim’s value.
Keep records of bills, receipts, pay information, treatment plans, and costs you paid yourself. A treating provider’s records may help document the injury and care, while employment records can support a claim for missed income. Notes about pain or limits on routine activities may also help preserve details, but they do not replace medical documentation.
Available coverage can constrain what is realistically recoverable, and a driver who is identified may still have limited insurance or resources. Multiple insurers may dispute responsibility for payment or seek reimbursement from a later recovery. An early settlement offer may not account for future care or the full effect of an injury. Before evaluating an offer, understand what losses it covers and whether accepting it would release further claims.
- Medical expenses and anticipated care supported by records
- Documented lost income or work-related effects
- The injury’s impact on daily activities and recovery
- Available coverage, liability evidence, and applicable legal limits
What evidence can support your recovery options?
Evidence can help establish that the crash occurred, identify the driver, show how it happened, and document your losses. A police report can preserve initial information, but it may not include every detail or resolve fault. If you have information about the vehicle, driver, location, or witnesses, share it with investigators and keep your own record of when and how you reported it.
Potential evidence includes photographs of the scene and visible injuries, nearby camera footage, witness names, medical records, bills, and communications with insurers. Video can be overwritten, and witnesses may become harder to locate, so prompt preservation requests can matter. Do not put yourself at risk to gather evidence or revisit a dangerous location.
Keep originals where possible and organize copies by date. Save messages, letters, claim forms, receipts, and notes from calls, including the name of the person you spoke with. For a crash involving a delivery or other commercial vehicle, additional business or vehicle records may matter; see Pedestrians Hit by Commercial Vehicles for related issues. Avoid posting details about the crash or your injuries publicly while a claim is being reviewed.
- Keep the report number and any information provided by investigators.
- Save photographs, witness details, bills, and insurer communications.
- Ask the relevant business or property owner to preserve potentially useful video or records.
How can you organize insurance claims and payments?
You can organize a hit-and-run claim by identifying possible payers, reporting the crash, and tracking expenses and communications. Different insurers may ask for overlapping information, and their positions can change as they review the investigation and your records. Keep each claim’s documents separate so you can tell which company is requesting or paying what.
When reporting the incident, provide accurate information and distinguish what you personally observed from what someone else told you. Ask how to submit records, who is handling the claim, whether the insurer needs an examination or other documentation, and what policy terms it is reviewing. Consider keeping a dated log of conversations and confirming important discussions in writing.
If medical bills are being submitted to health insurance or another benefit provider, keep track of payments, denials, and reimbursement requests. Do not assume a payment settles your injury claim or that one insurer’s decision binds another. Before signing a release or accepting a final settlement, read its scope and ask what claims or future payments it affects. A written offer and its supporting explanation are useful documents to review carefully.
- Create a folder or log for each insurer, policy, and claim number.
- Record bills, payments, denials, and any requests for reimbursement.
- Review releases and settlement terms before signing or accepting.
Why do deadlines and fault rules matter?
Deadlines and fault rules matter because missing a required filing or notice period can limit your options, and responsibility for the crash may affect recovery. The applicable time limit can depend on the type of claim, who may be responsible, and where the crash happened. Insurance policies can also impose notice or proof requirements separate from a court filing deadline.
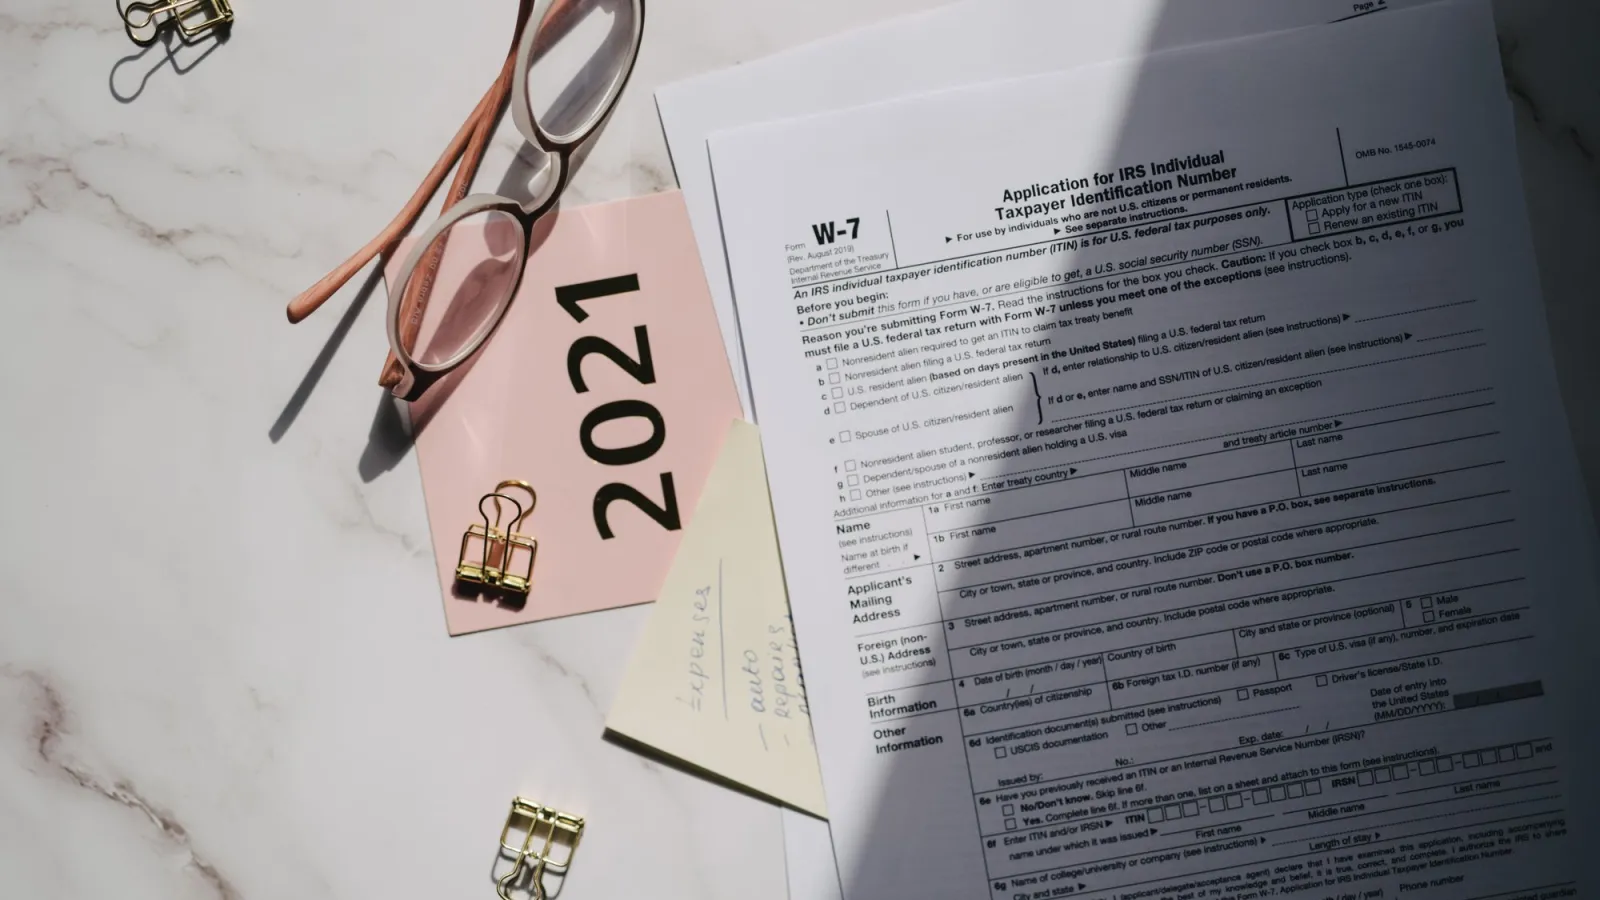
If a public agency or government employee may be involved, special notice procedures may apply. A victim compensation program can have a separate application process, and an insurer may ask you to report a hit-and-run promptly. These time requirements do not necessarily match one another. Keep written records of when you first notified each insurer or program.
Do not rely on a general online deadline to determine how much time remains for your claim. The crash date, the parties involved, policy language, and state law can all matter. If you are unsure which rules apply, gather the report, policies, and claim correspondence for a focused review. You can use the Contact page to ask about a free case evaluation, an insurance offer, or a deadline check.
Which recovery rules vary by state?
State law can affect the filing deadlines, fault rules, damage limits, insurance benefits, and notice procedures that apply to a pedestrian hit-and-run claim. States also differ in how uninsured motorist coverage applies to pedestrians and how medical or victim compensation benefits coordinate with other payments.
The location of the crash and the type of potential claim can affect which rules apply. Claims involving a government entity may have distinct notice procedures, while a private insurance claim may raise policy-specific requirements. Because these rules can change your options and the time available to act, check the law and policy terms that apply to your situation rather than relying on a general rule.
Frequently Asked Questions
Can I make a claim if the driver is never identified?
Possibly. Your own uninsured motorist coverage may apply, depending on policy terms and state law, and other options such as health coverage or a victim compensation program may be available. Report the incident and preserve documentation because insurers or programs may require particular proof.
Can I still recover if I may have been partly at fault?
Possibly, but the effect of shared fault depends on the state’s rules and the evidence. The driver’s conduct, your actions, and other circumstances may be considered. Do not assume that uncertainty about fault automatically ends a potential claim.
Will my health insurance pay for treatment after the crash?
Your health plan may cover eligible care under its terms, even while another claim is being investigated. Deductibles, co-pays, exclusions, and reimbursement rights may apply. Keep explanations of benefits and payment records.
Should I accept an insurance settlement offer right away?
A quick offer may not reflect all documented losses, especially if treatment or recovery is ongoing. Read any release carefully to understand which claims it closes and whether it affects future payments. You can request a written explanation of how the offer was calculated.
What if the hit-and-run involved a delivery or other work vehicle?
A commercial vehicle may involve additional insurance policies, business records, or other potentially responsible parties. The facts about the vehicle, its use, and the driver’s relationship to a business can matter. Preserve identifying information and mention the commercial connection when reporting the crash.
Next Steps
Use our free case-evaluation calculator to organize the details of the crash, review an insurance offer, or check what deadlines may apply. You can also request a consultation to discuss which recovery options may fit your circumstances. Talk with an attorney about your claim's value
Related Articles

Rideshare Accidents Involving Food Delivery Drivers
A crash involving a rideshare driver and a food delivery driver can raise questions about fault, app status, and which insurance policies may apply. Learn what evidence can help clarify your options.

Arbitration Clauses in Rideshare Terms of Service
A rideshare arbitration clause may affect how you pursue certain injury claims, but its reach depends on the agreement, the parties, and the facts. Learn what to check after a crash.

Robotaxi and Driverless Ride Accidents: Liability Questions
Responsibility for a robotaxi crash depends on what caused it and who had a role in the vehicle’s operation, design, or upkeep. Learn which evidence may help clarify your options.
