

In this blog
- What does “degenerative” mean on an MRI report?
- Can an MRI show whether the crash caused your symptoms?
- What information can help explain the MRI finding?
- How should you respond when the insurer says the findings are degenerative?
- When may a medical or legal review be useful?
- Do state laws affect an injury claim involving degenerative findings?
- Frequently Asked Questions
- Next Steps
“My back felt fine before the crash, but now the insurer says my MRI shows degeneration and won’t connect it to the collision.” That label is the insurer’s interpretation, not a complete medical explanation. Ask your treating clinician to explain the findings in context, keep records of your symptoms and care, and avoid guessing about cause or timing when speaking with the insurer.
Key Facts
- “Degenerative” describes changes that can develop over time; it does not alone establish when symptoms began.
- An MRI image needs to be considered alongside your symptoms, examination, and medical history.
- An insurer’s description of a scan is not the same as an independent medical conclusion.
- Consistent records can help show when symptoms appeared and how they changed.
- The rules and deadlines for injury claims depend on the state and circumstances.
What does “degenerative” mean on an MRI report?
“Degenerative” generally describes changes in body structures that may develop over time, such as changes involving discs or joints. The word describes an imaging appearance; on its own, it does not tell you whether a finding caused pain, when it began, or whether a collision aggravated a condition.
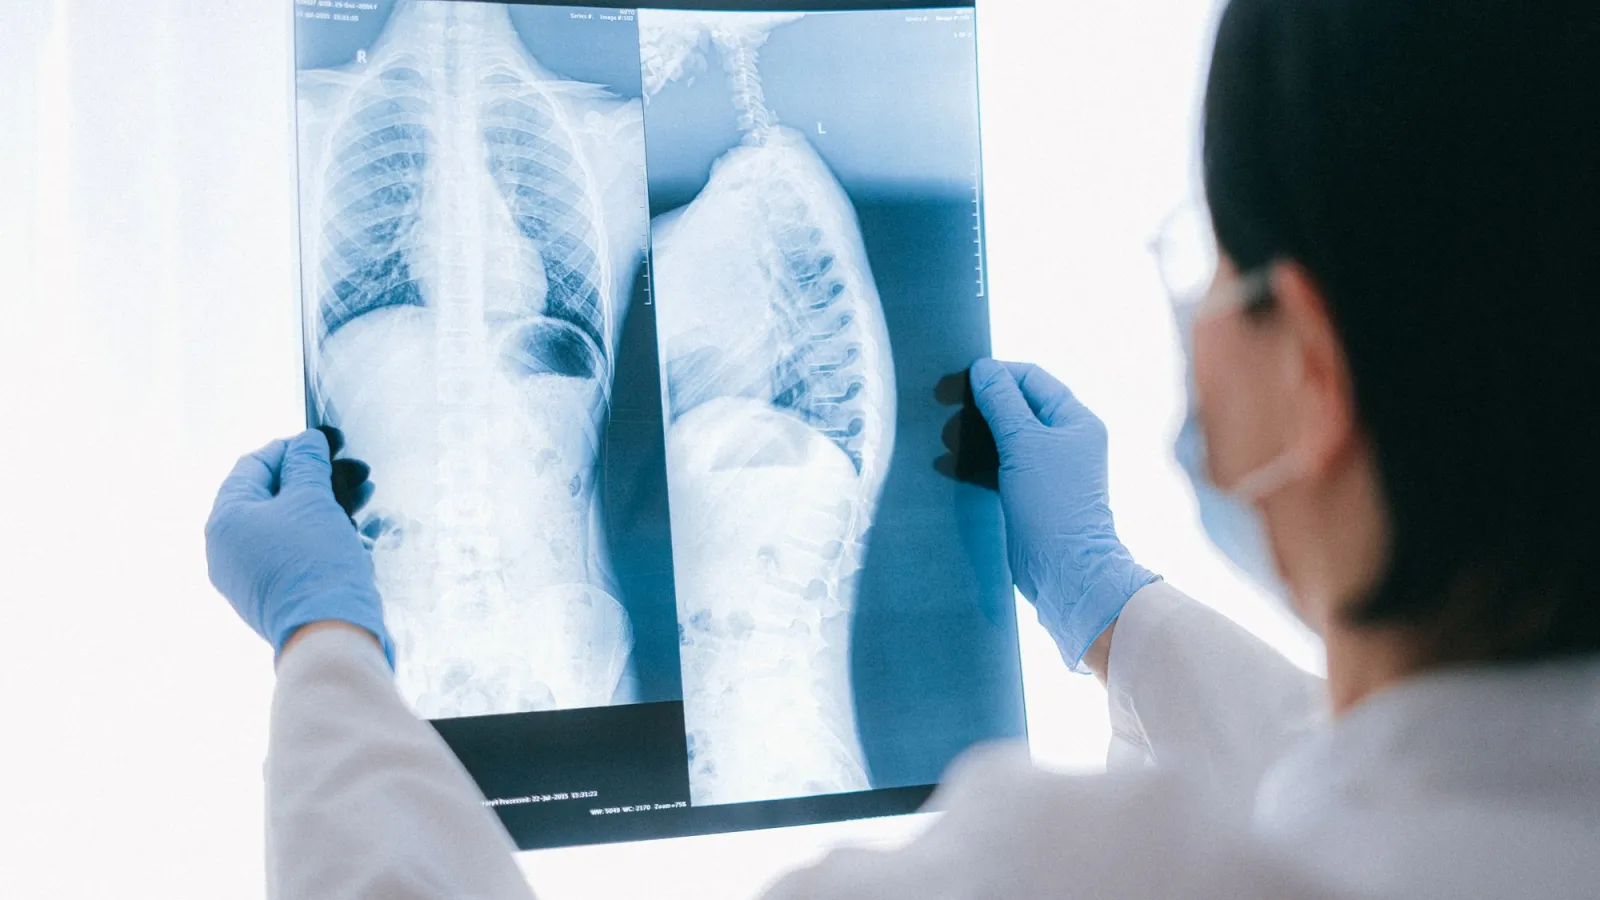
MRI reports can include findings that are common in people without symptoms, as well as findings that may matter clinically. The significance depends on the specific report and your health history. A radiologist’s description is one part of the record, not a diagnosis of how the crash affected you.
An insurer may focus on the word “degenerative” to argue that your symptoms predated the crash. That is the insurer’s position, not a complete determination of the medical or legal issues. Your clinician can explain what the scan shows and how it relates—or does not relate—to your symptoms and examination.
Can an MRI show whether the crash caused your symptoms?
An MRI may help identify physical findings, but it usually cannot establish by itself when those findings developed or what caused them. A clinician interprets the images alongside your symptoms, examination, prior health information, and the timing of your complaints.
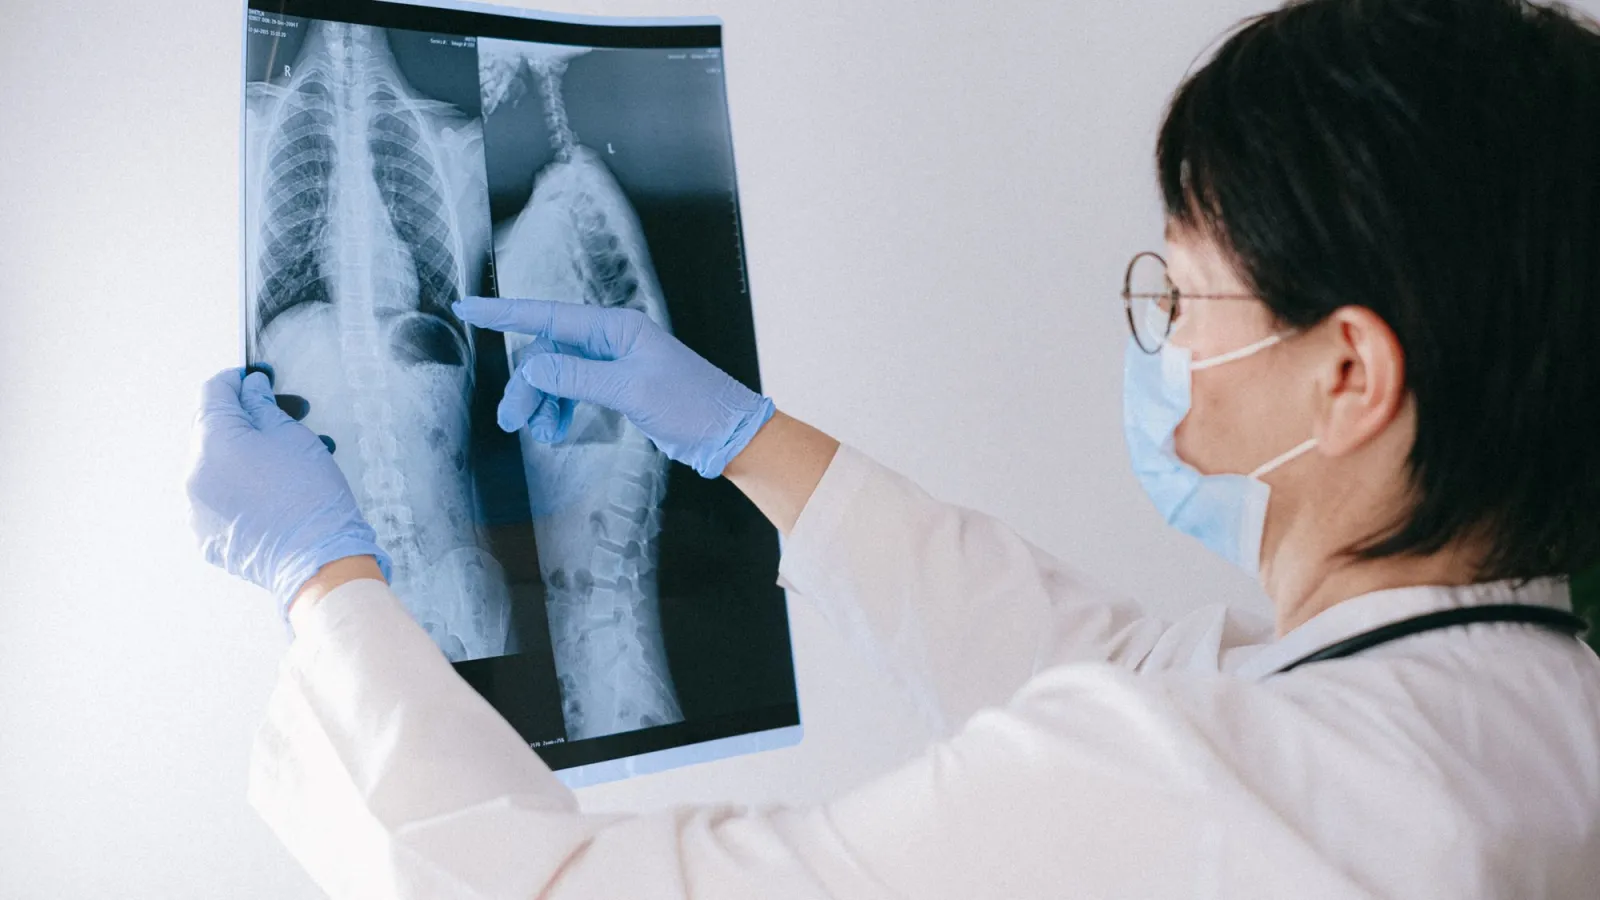
If pain, numbness, or other symptoms began after a collision, describe the timing accurately to your medical provider. Explain what you noticed before the crash, what changed afterward, and whether symptoms have improved, worsened, or shifted. Avoid claiming that the scan proves a cause unless your clinician has explained that conclusion.
A pre-existing condition and a new injury or worsening of symptoms are not necessarily the same thing. Whether a collision contributed to your condition depends on the evidence and applicable law. That can matter in many car accident claims, including cases where imaging findings are part of a broader medical record.
What information can help explain the MRI finding?
Clear, consistent medical records can help put an MRI finding in context. Useful information may include your symptoms before and after the crash, examination findings, treatment recommendations, and your clinician’s explanation of the scan. Records cannot determine how an insurer or court will view the claim, but they can make the medical timeline easier to understand.
You can organize the information in a practical sequence:
Keep your MRI report and ask your provider to explain terms you do not understand.
Write down when symptoms began, where you feel them, and how they affect daily activities.
Tell providers about relevant earlier symptoms, conditions, and treatment; do not leave out history to make the record sound stronger.
Save appointment summaries, treatment instructions, and communications from the insurer.
For example, after a rear-end collision, note when symptoms first appeared and report changes to your clinician. Your records should reflect your actual experience. If there was a gap in care, explain the reason honestly rather than trying to fill it with assumptions.
How should you respond when the insurer says the findings are degenerative?
Respond calmly, stick to what you know, and avoid accepting the insurer’s medical conclusion as established fact. You can say that you are discussing the MRI with your treating clinician and ask the adjuster to identify the documents or medical opinion supporting the insurer’s position.
Do not speculate about what the scan proves, and do not sign a medical release or settlement document without understanding what it covers. An authorization may give access to records beyond the crash-related treatment, while a settlement may affect future claims. The wording and legal effect depend on the document and applicable law.
Keep notes of calls, including the date, the person you spoke with, and what was requested or said. When sending records, keep a copy and note what you provided. If the insurer asks for a recorded statement or makes an offer, you can take time to understand the request and its implications rather than responding under pressure.
The same care applies whether the collision was a head-on crash or another type of car accident. The medical details and claim circumstances matter more than a label alone.
When may a medical or legal review be useful?
A medical review may help when you do not understand the report, your symptoms do not match how the insurer describes the findings, or you are unsure what care to pursue. Ask your treating clinician to explain the MRI in relation to your history and examination. Do not stop or change treatment based only on an insurer’s statement.
A legal review may be useful if the insurer disputes whether the crash contributed to your symptoms, requests a broad release, or presents an offer while your medical picture is still developing. A lawyer can review the available records and explain how state rules may apply, but no one can determine the result from the word “degenerative” alone.
Keep copies of the crash-related records and insurer communications so a reviewer can understand the sequence. An evaluation can also help identify questions about claim documents and applicable deadlines. If you are considering a claim involving a car accident, bring the MRI report and any offer or release you have received to the review.
Do state laws affect an injury claim involving degenerative findings?
Yes. State law can affect deadlines, fault rules, damage limits, and notice requirements, and the details may vary by state and by claim. The medical meaning of an MRI finding is a separate question from how state law treats evidence of a prior condition or a claimed worsening.
Because no state or claim details are provided here, no specific deadline or legal rule can be identified. A state-specific review can clarify which rules apply and whether any time-sensitive requirements need attention.
Frequently Asked Questions
Does a degenerative MRI finding mean you had symptoms before the crash?
No. The term describes an imaging finding and does not, by itself, establish whether you had symptoms or when they began. Your history and clinical evaluation provide important context.
Should you tell your doctor about earlier pain or treatment?
Yes, give your provider an accurate health history, including earlier symptoms or treatment. That information helps the clinician interpret the MRI and document how your condition changed.
Can you ask the insurer what supports its position?
You can ask the adjuster to explain the basis for the insurer’s view and identify the records or medical opinion it relies on. Keep the request and response with your claim documents.
What if your symptoms continue after the insurer makes an offer?
An offer does not tell you whether your symptoms will resolve or what future care may involve. Before signing a release, understand what claims it covers and consider getting a medical and legal review of the situation.
Next Steps
If an insurer is relying on a “degenerative” MRI label or has sent you an offer, you can request a consultation to review the records, offer, and any applicable deadlines. Bring the MRI report and insurer communications so the review can focus on your specific questions.

Related Blog

Colorado Motorcycle Crash: Does Lane Filtering Make Me at Fault?
Lane filtering alone does not decide fault after a Colorado motorcycle crash. The circumstances, applicable rules, evidence, and Colorado’s comparative-fault system all matter.

Hit by a Drunk Driver in Ohio: Can I Sue the Bar?
A bar is not automatically liable when a customer drives drunk. Whether you can bring a claim depends on the facts, evidence, and Ohio law.

Can I Sue the Other Driver in Florida, or Am I Stuck With PIP?
PIP may cover some losses after a Florida crash, but it does not automatically prevent a claim against another driver. The facts, available evidence, and Florida’s fault rules matter.
