

In this blog
- What does it mean when an adjuster asks you to see their doctor?
- Do you have to attend an insurance medical examination?
- How can you respond to the adjuster’s request?
- What should you expect if you attend the exam?
- How can you protect your claim and your medical information?
- Why can the rules differ depending on where you live?
- Frequently Asked Questions
- Next Steps
“The adjuster says I have to see their doctor before they’ll move forward. Do I?” Not automatically: an insurer’s request alone may not require you to attend, but your policy, the type of claim, and state rules can matter. Ask for the request and its basis in writing, and check the possible consequences before you agree or decline.
Key Facts
- An insurer-selected medical exam is generally for evaluating a claim, not providing treatment.
- Your own policy may have terms about attending an examination.
- A third-party insurer’s request and an examination ordered during a lawsuit are different situations.
- Ask what the exam involves, who will receive the results, and what happens if you decline.
- Keep following your treating provider’s care plan and keep records of your symptoms and appointments.
What does it mean when an adjuster asks you to see their doctor?
It usually means the insurer wants a medical evaluation to help assess your injuries or the claim. The appointment may be called an independent medical examination, or IME, but the doctor is selected or arranged by the insurer rather than being your treating provider.
The examiner may ask about the collision, your symptoms, and your medical history, and may conduct an examination. The insurer may use the report when considering whether your injuries relate to the crash, what care may be needed, or how to evaluate the claim. The exam is not a substitute for treatment, and you should not expect the examiner to manage your care.
A request can come from your own auto insurer or from the other driver’s insurer. Those are not necessarily the same situation: your policy may contain provisions about examinations, while a third-party adjuster generally does not control your medical care simply by making a request. For background on injury claims after a crash, see our Car Accidents page.
Do you have to attend an insurance medical examination?
You may have to attend if an applicable policy term or legal process requires it, but an adjuster’s request by itself does not settle that question. Before accepting or refusing, find out whether the request is from your insurer or the other driver’s insurer and what rule or policy provision the insurer says applies.
If you have a claim under your own coverage, the policy may require cooperation or an examination in some circumstances. Declining without checking could affect how the insurer handles that claim. If the request comes from the other driver’s insurer, ask what the insurer believes gives it a right to require an exam and what consequences it claims could follow if you do not attend.
An examination ordered as part of a lawsuit is a separate matter from an adjuster’s informal request. Court rules and state law may govern that process. If you have received legal papers, a formal notice, or a request tied to litigation, get advice about the specific document rather than treating it as an ordinary appointment request.
How can you respond to the adjuster’s request?
You can respond by asking for the request, its purpose, and any claimed requirement in writing before deciding what to do. A clear written record can help you understand the request and avoid relying on an unclear phone conversation.
Use these steps to clarify what is being asked:
- Ask whether the requesting insurer is your insurer or the other driver’s insurer, and identify the claim involved.
- Request the proposed examiner’s name, the appointment details, what the exam will include, and who will receive the report.
- Ask the insurer to identify the policy language or legal process it relies on and explain any claimed consequences of declining.
- Review the request with your policy documents and, if needed, a lawyer before confirming or refusing.
Do not ignore a written request, but you do not need to guess at its meaning. If you are unsure how the request fits into an injury claim, a Consultation can help you understand what to ask about. Keep copies of messages and note when you speak with the adjuster.
What should you expect if you attend the exam?
If you attend, expect an evaluation rather than treatment, and ask in advance how it will be conducted. The exact process can depend on the examiner and the issues the insurer wants reviewed, so confirm the appointment’s length, scope, and any instructions before you go.
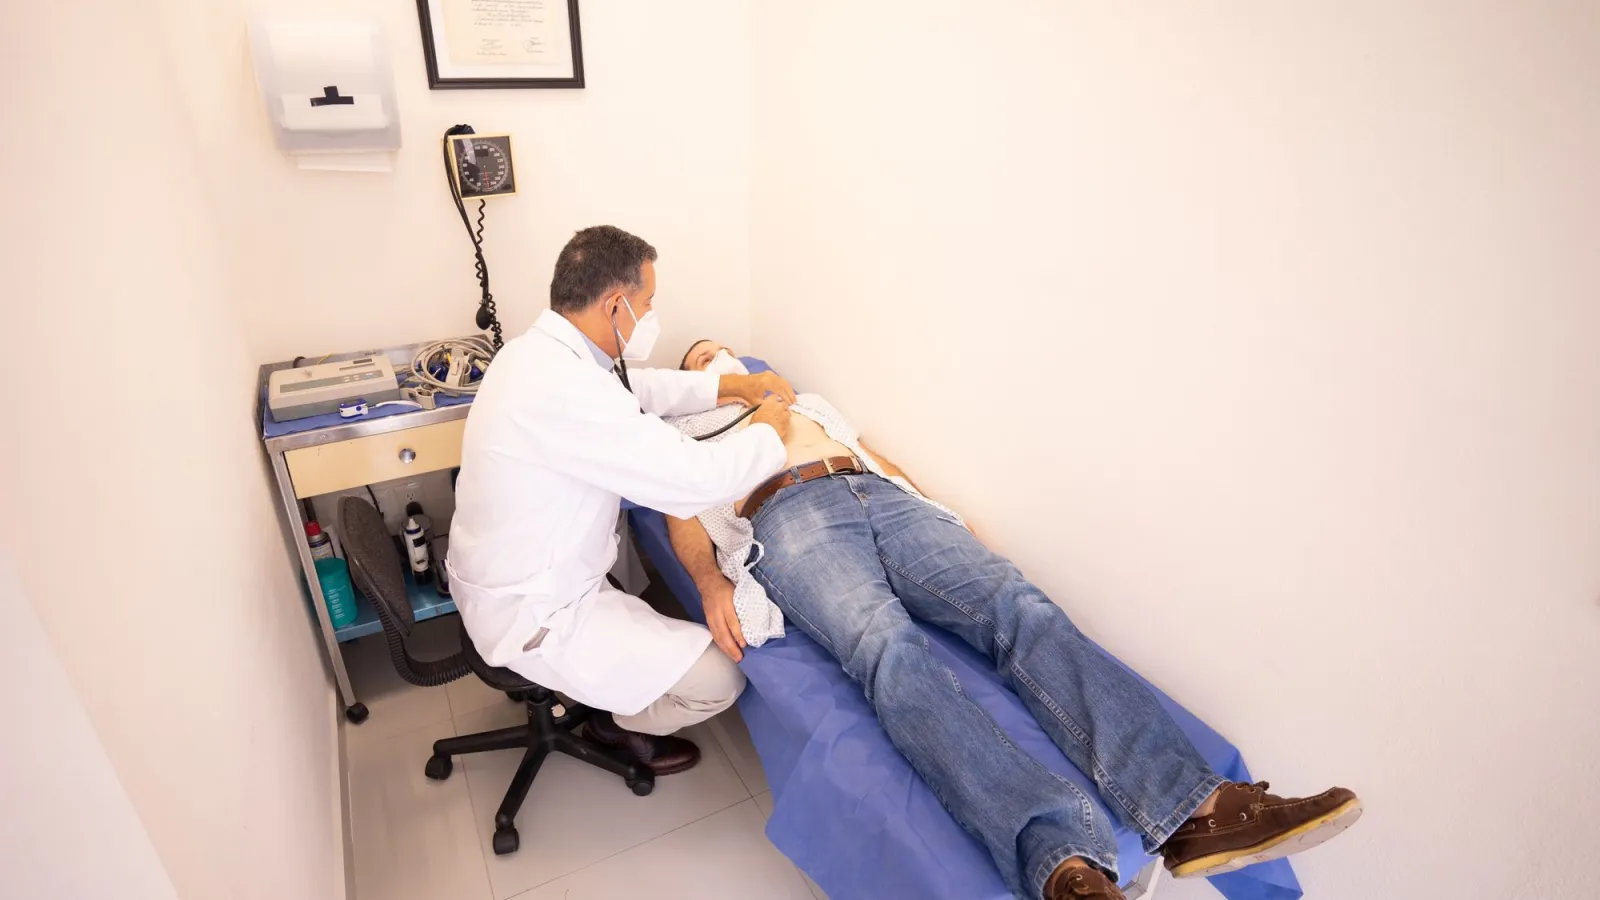
Answer questions truthfully and describe your symptoms as accurately as you can, including what has improved and what has not. Do not guess when you do not know an answer. You can bring a written list of medications, providers, and symptoms so you can give clear information without relying on memory.
Ask whether a companion may attend or whether the appointment may be recorded; do not assume the answer is the same in every situation. Keep your own notes about what happened and any follow-up the insurer requests. If the exam causes discomfort or you believe an instruction is unclear, explain that at the time and make a note of it afterward.
Continue care with your own treating provider. An insurer-selected examiner does not replace your doctor, and the examiner’s conclusions may differ from those of the professionals treating you. Different crashes, including Rear-End Collisions, can involve different reported symptoms and medical issues.
How can you protect your claim and your medical information?
You can protect your interests by keeping the exam request, your responses, and your medical records organized while continuing appropriate care. The insurer’s request does not mean you should stop treatment or change what you tell your providers.
Before signing anything, read what it authorizes. A document that allows access to medical records may be broader than permission for a single examination. Ask what records are requested, who may see them, and whether the authorization can be limited; do not sign a form you do not understand.
Keep copies of appointment notices, emails, letters, and any forms you receive. Record your symptoms and how they affect everyday activities, and keep bills or other claim-related documents. Be accurate and consistent when speaking with providers and the insurer, and promptly correct any factual mistake you notice in a record or message.
If the insurer connects the exam to a settlement offer, consider the medical evaluation alongside your treatment status, documented losses, and any unresolved symptoms. You do not have to make a rushed decision just because an adjuster requests an appointment or asks for a response. A lawyer can review the request, offer, and relevant policy language with you.
Why can the rules differ depending on where you live?
State law and insurance policy terms can affect whether an insurer may require an examination, how a request must be handled, and what consequences may follow if you decline. Rules can also differ between a claim under your own coverage and a claim against another driver.
Court procedures may apply if an examination is requested during a lawsuit. Because the details depend on the claim and the governing rules, check the written request and relevant policy language rather than relying on a general answer. A local legal professional can help explain how those rules apply to your situation.
Frequently Asked Questions
Is an insurer-requested exam the same as seeing my own doctor?
No. The insurer-requested appointment is for evaluating the claim, while your own provider is responsible for your care. Keep following your treating provider’s advice and direct treatment questions to that provider.
Can I ask who will receive the exam report?
Yes. Ask the insurer in writing who will receive the report and how it may be used. Also review any forms you are asked to sign before providing authorization.
What if I already have an appointment with my treating doctor?
Tell the adjuster about the existing appointment and ask how it relates to the requested exam. Do not cancel or change treatment without discussing your care with your provider.
Could the exam affect a settlement offer?
The insurer may consider the report when evaluating the claim or an offer. You can ask for a copy of the report and review it alongside your treatment information and documented losses before responding.
What if I disagree with the examiner’s report?
Ask the insurer how to obtain and respond to the report, and keep records of any factual errors or differences from your treating provider’s findings. A lawyer can explain options for addressing the disagreement in your claim.
Next Steps
If an adjuster has asked you to attend an exam or made an offer, request a free case evaluation to discuss the request, review the offer, or check for deadlines that may apply. You can arrange a Consultation to talk through your next steps without pressure.
Related Guides

Related Blog

Colorado Motorcycle Crash: Does Lane Filtering Make Me at Fault?
Lane filtering alone does not decide fault after a Colorado motorcycle crash. The circumstances, applicable rules, evidence, and Colorado’s comparative-fault system all matter.

Hit by a Drunk Driver in Ohio: Can I Sue the Bar?
A bar is not automatically liable when a customer drives drunk. Whether you can bring a claim depends on the facts, evidence, and Ohio law.

Can I Sue the Other Driver in Florida, or Am I Stuck With PIP?
PIP may cover some losses after a Florida crash, but it does not automatically prevent a claim against another driver. The facts, available evidence, and Florida’s fault rules matter.
